Clarity in Penalty Notices Under Section 271(1)(c) of the Income Tax Act, 1961 Emphasized by the Court
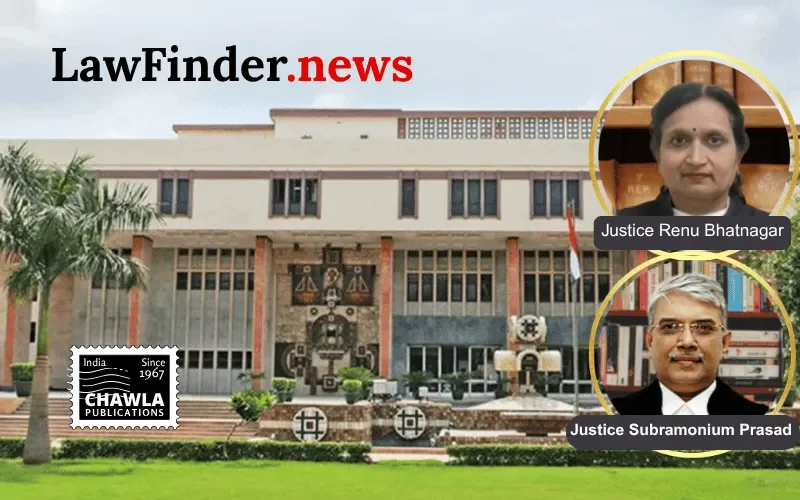
In a significant judgment, the Delhi High Court, comprising Justices Dinesh Mehta and Rajneesh Kumar Gupta, dismissed the appeal filed by the Principal Commissioner of Income Tax against Vitasta Estates Pvt. Ltd., thereby upholding the decision of the Income Tax Appellate Tribunal (ITAT) that set aside the penalty imposed on the assessee under Section 271(1)(c) of the Income Tax Act, 1961.
The court was presented with the question of whether the penalty proceedings initiated by the Assessing Officer (AO) were valid, given that the notice issued did not specify whether the penalty was for concealment of income or for furnishing inaccurate particulars. The proceedings pertained to the assessment year 2008-09, where the respondent-assessee had originally declared a revenue loss, which was later revised to a capital loss.
During the hearing, it was highlighted that the AO had issued a notice under Section 271(1)(c) on December 23, 2010, which ambiguously stated that the assessee had "concealed the particulars of your income or furnished inaccurate particulars of such income." This lack of specificity was the crux of the assessee's defense, arguing that the notice was foundational and required clarity for the assessee to mount an adequate defense.
The High Court, referencing a consistent line of judgments including those from the Karnataka High Court and the Supreme Court, reiterated the necessity for the AO to clearly indicate the specific charge under Section 271(1)(c) when issuing a penalty notice. The court observed that the use of the word "or" in the notice rendered it ambiguous and void, as the assessee was not properly informed of the charges against them.
The court rejected the revenue's argument that the notice was merely procedural and any deficiency should have resulted in a remand rather than annulment. The court upheld the Tribunal's decision, emphasizing that proper notice is a jurisdictional requirement and not a mere formality.
This judgment reinforces the principle that penalty proceedings under Section 271(1)(c) demand precise and clear notices, reflecting the specific charge against the assessee, to ensure fairness and uphold the principles of natural justice.
Bottom Line :
Income Tax - Penalty proceedings under Section 271(1)(c) of the Income Tax Act, 1961 - Notice issued by the Assessing Officer must specifically mention the precise limb of Section 271(1)(c) (either concealment of income or furnishing inaccurate particulars) under which penalty is proposed to be levied. A vague or unclear notice renders the penalty proceedings void.
Statutory provision(s): Section 271(1)(c) of the Income Tax Act, 1961