Court finds Assessing Officer's initiation of Section 148 proceedings arbitrary and contrary to settled judicial precedents, emphasizing finality in tax adjudication.
In a significant ruling dated September 14, 2026, the Delhi High Court (Division Bench) stayed the income tax proceedings initiated against GoDaddy.com LLC under Section 148 of the Income Tax Act, 1961. The proceedings pertained to the tax treatment of income earned by GoDaddy from domain registration services provided to Indian customers.
GoDaddy, represented by Senior Advocate Mr. Sachit Jolly, contended that its income from domain registration does not amount to "royalty" or "Fee for Technical Services" under Section 9(1)(vi) of the Income Tax Act. The petitioner stressed that it merely acts as a registrar facilitating domain registrations and does not own or hold proprietary or licensing rights to any domain names. Consequently, GoDaddy argued that it cannot transfer or confer rights to use domain names, thereby making the tax demand untenable.
The petitioner's stand was bolstered by previous decisions of the Delhi High Court and the Income Tax Appellate Tribunal (ITAT) for assessment years 2013-14 through 2022-23, which consistently held that GoDaddy's income from domain registration does not constitute royalty or fees for technical services. The Revenue Department had not challenged these ITAT orders, lending finality to the position.
Despite these precedents, the Assessing Officer initiated proceedings under Section 148 based on a notice dated March 30, 2026, alleging undisclosed income. The petitioner submitted detailed replies, including judicial precedents and the absence of any Permanent Establishment (PE) in India, which was also the subject of a certificate issued under Section 197 at a nil withholding tax rate. However, the Assessing Officer rejected these submissions summarily by an order dated June 30, 2026.
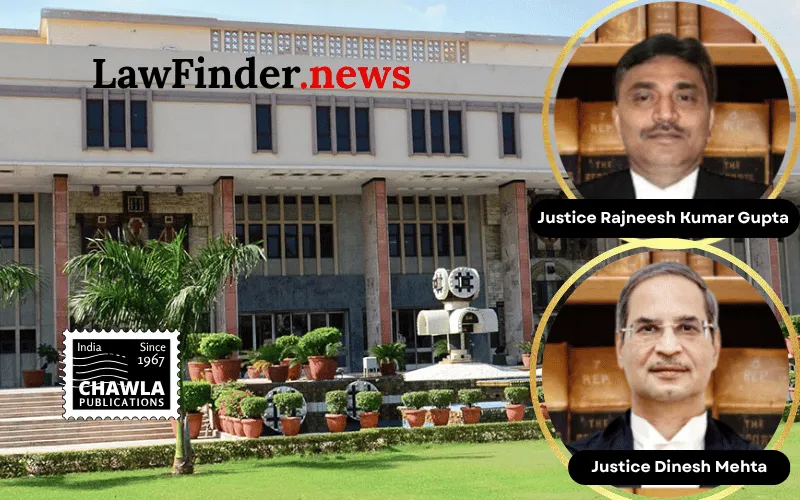
The Court observed that the Assessing Officer's conduct was arbitrary and lacked objectivity. The bench, comprising Mr. Justice Dinesh Mehta and Mr. Justice Rajneesh Kumar Gupta, highlighted that the Assessing Officer appeared to be motivated by revenue considerations, disregarding the principles of certainty and finality which are cornerstones of the tax adjudication system.
The Court noted that GoDaddy's case had been examined repeatedly through scrutiny assessments under Section 143(3), and the initiation of proceedings under Section 148 amounted to a mere change of opinion, which is not a permissible ground for reopening assessments.
Consequently, the Court stayed the proceedings under Section 148 of the Income Tax Act until the next hearing scheduled for January 20, 2027, thereby providing temporary relief to GoDaddy from the contested tax demand.
This judgment underscores the importance of adherence to settled legal principles and judicial precedents by tax authorities and reinforces the protection against arbitrary reopening of assessments under the Indian tax regime.
Bottom Line:
Income Tax - Proceedings under Section 148 of the Income Tax Act, 1961 stayed due to arbitrary and non-objective approach of Assessing Officer, who ignored judicial precedents and finality of previous assessments.
Statutory provision(s):
Income Tax Act, 1961 Sections 9(1)(vi), 148, 148A, 197