Court Rules Appeals Under Section 130 of Customs Act Maintainable in Cases of Alleged Fraudulent Drawback Claims; Rejects CESTAT's Narrow Interpretation of Valuation and Third-Party Remittance Issues
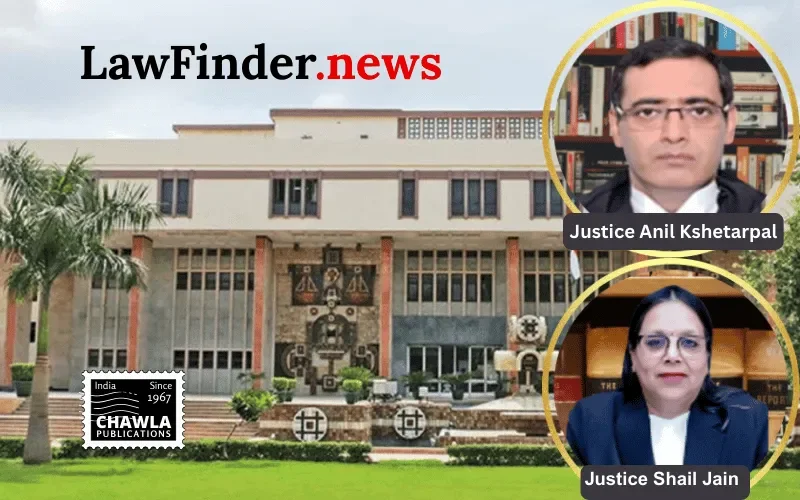
In a significant judgment delivered on November 4, 2026, the Delhi High Court in a Division Bench comprising Justices Anil Kshetarpal and Shail Jain set aside the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) order that had favored exporters accused of fraudulent availing of customs drawback and export incentives. The Court restored the original order passed by the Commissioner of Customs (Export), Tughlakabad, except for a penalty imposed on an individual which remained set aside due to procedural lapses.
The case arose from investigations by the Directorate General of Revenue Intelligence (DRI) into alleged fraud by several exporters including M/s G.D. Manglam Exim Pvt. Ltd. (now M/s Welldone Exim Pvt. Ltd.) and others, who exported readymade garments to the UAE and other countries from 2008-09 to 2014. The exporters had claimed customs duty drawback and export incentives under schemes such as Focus Product Scheme (FPS) and Focus Market Scheme (FMS), based on shipping bills declaring inflated values and showing third-party remittances as export proceeds.
The DRI's probe revealed a complex network of transactions involving fictitious domestic suppliers and overseas entities, including diamond traders, that facilitated overvaluation of goods and round-tripping of funds. It was found that third-party remittances, not linked to actual overseas buyers, were used to claim higher drawback benefits. Punjab National Bank (PNB) had issued Bank Realisation Certificates (BRCs) for such payments but later cancelled 1,650 BRCs upon discovery of irregularities, a move challenged unsuccessfully by exporters in civil courts.
The Commissioner of Customs adjudicated that the cancelled BRCs indicated non-realisation of genuine export proceeds, confirming demand for recovery of excess drawback and duty credit scrips, along with penalties. However, CESTAT reversed this, holding that Customs could not question third-party remittances without RBI or FEMA invalidation and that without formal re-determination of export value under Section 14 of the Customs Act, the overvaluation allegations could not justify recovery.
The Revenue challenged CESTAT's order before the Delhi High Court, which examined four key issues: the maintainability of appeals under Section 130 of the Customs Act in cases involving overvaluation and third-party remittances; the jurisdiction of Customs authorities to scrutinize third-party payments; the binding effect of civil court decrees on Customs proceedings; and the interpretation of Section 28AAA concerning duty credit scrips obtained by fraud.
Key findings of the Delhi High Court include:
1. Maintainability of Appeals: The Court clarified that Section 130 excludes High Court jurisdiction only in matters involving determination of value for assessment purposes. Since the present dispute concerned entitlement to retain drawback and export benefits based on alleged fraudulent declarations, not reassessment of export value under Section 14, the appeals were maintainable.
2. Third-Party Remittances: Customs authorities have jurisdiction to examine whether remittances credited to exporters are genuine sale proceeds linked to exported goods, notwithstanding RBI's regulatory role under FEMA. Receipt of funds in bank accounts alone does not conclusively establish legitimacy. The Court emphasized that Customs' enquiry is limited to statutory entitlement under the Customs Act and does not extend to enforcement of foreign exchange regulations.
3. Appellate Duty of CESTAT: The Court held that when an appellate authority reverses a detailed adjudication order based on extensive documentary and testimonial evidence, it must critically analyze the material findings and record reasons. CESTAT erred by not adequately examining the cumulative evidence supporting the original adjudication.
4. Effect of Civil Judgment: The civil court's declaratory decree invalidating PNB's cancellation of BRCs binds only parties to that suit, not the Customs Department, which was not a party. Hence, the decree does not conclusively affect Customs' independent statutory rights or proceedings.
5. Section 28AAA on Duty Credit Scrips: Liability under Section 28AAA for fraudulent duty credit scrips does not depend on invalidation of scrips against subsequent users. The Court held that statutory ingredients must be examined on record and cannot be dismissed for lack of separate proceedings against all users.
6. Penalty on Individual Noticee: The Court upheld the CESTAT's setting aside of penalty on Shri Nitin Gupta for non-compliance with mandatory procedural safeguards under Section 124 of the Customs Act, including notice, supply of documents, and hearing.
The Court concluded that the CESTAT's order was legally unsustainable and restored the original order by the Commissioner of Customs (Export) except for the penalty on Shri Nitin Gupta. The judgment reinforces Customs authorities' power to investigate complex fraud involving export incentives and clarifies the limited scope of appellate intervention under Section 130.
This ruling is expected to have far-reaching implications for export incentive fraud cases, emphasizing rigorous scrutiny of export proceeds and documentation by Customs and affirming their autonomy from RBI's foreign exchange regulatory framework in such matters.
Bottom Line:
Customs - Drawback and export incentive fraud - High Court held appeals under Section 130 of Customs Act maintainable where dispute concerned fraudulent availment of drawback and duty credit benefits, and not determination of value for purposes of assessment - Customs authorities are competent to examine whether third-party remittances truly represent sale proceeds for exported goods while considering entitlement to retain drawback - CESTAT erred in treating civil decree regarding cancellation of BRCs as binding on Customs though Customs Department was not party to suit - Order of CESTAT set aside and Order-in-Original restored except penalty on one noticee which remained set aside for breach of natural justice.
Statutory provision(s):
Customs Act, 1962 Sections 14, 28AAA, 75, 75A, 124, 130; Customs and Central Excise Duties Drawback Rules, 1995 Rules 16, 16A; Foreign Trade (Development & Regulation) Act, 1992 Section 11; Specific Relief Act, 1963 Sections 34, 35