Court holds prosecution under Sections 276D/277 of Income Tax Act unsustainable after appellate tribunal sets aside assessment order; quashes multiple complaint cases against company and its directors
In a significant judgment delivered on September 2, 2026, the Gauhati High Court quashed three criminal complaint cases registered against M/s Flamingo Breweries Pvt. Ltd. and its two directors, Sanju Phangcho and Bijoy Phangcho, under Sections 276D and 277 of the Income Tax Act, 1961. The complaints, which alleged willful failure to produce accounts and false statements in income tax verification for the assessment year 2016-17, were found to have no legal foundation following the setting aside of the underlying assessment order by the Income Tax Appellate Tribunal (ITAT).
The prosecution cases, registered as C.R. Case Nos. 1103C/2019, 1099C/2019, and 1100C/2019, were instituted based on an assessment order dated December 21, 2018, which determined taxable income significantly higher than that declared by the petitioner company. The Income Tax Department alleged that the company and its directors deliberately evaded taxes and failed to comply with statutory notices.
However, the petitioners challenged the assessment order before the Commissioner of Income Tax (Appeals) and subsequently before the ITAT. The Tribunal, by order dated March 18, 2021, set aside the appellate order and remanded the matter back to the Assessing Officer for fresh adjudication, allowing the petitioners to submit further evidence and accounts. This effectively nullified the foundation of the criminal complaints.
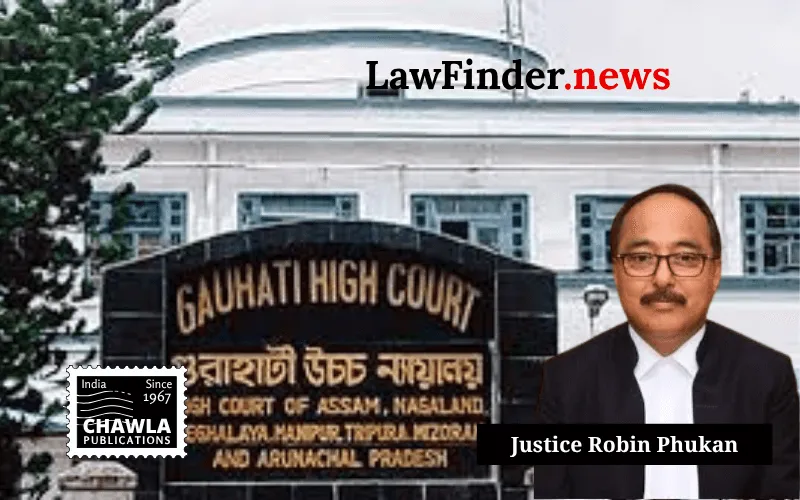
The Gauhati High Court, presided over by Justice Mr. Robin Phukan, applied the legal principle "sublato fundamento cadit opus" (when the foundation is removed, the structure falls), holding that criminal prosecution cannot survive when the basis of the complaint-the assessment order-has been set aside on merits. The Court also noted that separate complaints against individual directors for the same offence without implicating the company are not maintainable, referencing the Supreme Court's ruling in Aneeta Hada v. Godfather Travels & Tours (P) Ltd. (2012).
The Court further distinguished the prosecution from penalty proceedings, observing that while penalty and prosecution can proceed simultaneously, if the factual foundation of concealment or false statement is negated by the Tribunal, continuing criminal proceedings becomes an abuse of process. The Court relied on landmark Supreme Court decisions including K.C. Builders v. Assistant Commissioner of Income Tax (2004) and G.L. Didwania v. Income Tax Officer (1995).
Responding to the Income Tax Department's contention that prosecution can continue independently of assessment or penalty proceedings, the Court reaffirmed that the presumption of culpable mental state under Section 278E of the Income Tax Act is rebuttable and applies only during the trial stage, not before filing the complaint. Since the appellate order overturned the basis of the prosecution, no valid cause of action remained.
Consequently, the Court allowed the criminal petitions filed by the company and the directors, quashing all three complaint cases. The parties were directed to bear their own costs.
This judgment underscores the importance of the appellate process in tax litigation and sets a precedent that criminal prosecutions under the Income Tax Act cannot proceed if the underlying assessment order is overturned on substantive grounds by the appellate authorities.
Bottom Line:
Criminal prosecution under Sections 276D/277 of the Income Tax Act is not sustainable when the underlying assessment order is set aside on merits by the appellate authority or tribunal, as the foundation of the prosecution collapses.
Statutory provision(s):
Income Tax Act, 1961 Sections 276D, 277, 278B, 278E; Code of Criminal Procedure, 1973 Section 482
M/s Flamingo Breweries Pvt. Ltd. v. Income Tax Deptt., (Gauhati) : Law Finder Doc Id # 2974706