Court Dismisses Challenge to Search Authorization and Procedural Grounds; Grants Petitioner 45 Days to Respond to Show-Cause Notice
In a significant judgment dated September 3, 2026, the Gauhati High Court dismissed the writ petition filed by M/s HD Associates challenging a demand-cum-show-cause notice issued under the Goods and Services Tax Act, 2017 (CGST Act). The petitioner had questioned the legality of a search and seizure operation conducted on February 1, 2024, and the subsequent demand notice for alleged suppression of taxable supplies for multiple financial years from 2021-22 to 2024-25.
The petitioners contended that the search authorization under Section 67 of the CGST Act lacked valid reasons to believe and was not furnished to them, rendering the authorization void ab initio. They also challenged procedural aspects, including the absence of a Document Identification Number (DIN) on the search authorization and the initiation of demand proceedings under Sections 74 and 74A without prior scrutiny under Section 61. Additionally, the petitioner argued that the consolidation of notices across multiple financial years violated the statutory scheme, particularly Section 75(13), which prohibits double penalties.
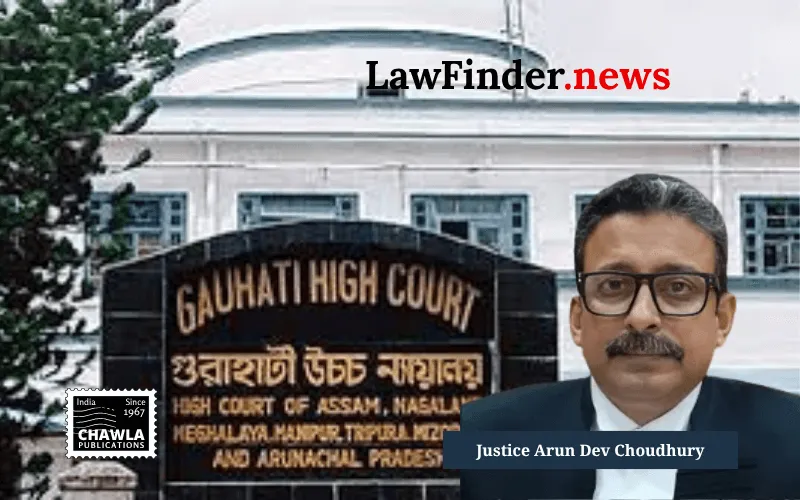
Justice Arun Dev Choudhury, presiding over the case, examined the statutory provisions and relevant facts. The Court noted that while the petitioner was not provided the reasons to believe prior to the search-an omission not mandated by the statute-the contemporaneous existence of such reasons is the key factor in validating the authorization. The Court held that the absence of prior disclosure does not invalidate the search authorization if reasons existed at the time of issuance of FORM GST INS-01.
Regarding the DIN issue, the Court observed that although the search authorization lacked a DIN, the question of whether this omission was fatal or could be regularized is a factual matter for the adjudicating authority. The Court refrained from quashing the notice solely on this ground.
Addressing the contention that demand proceedings under Sections 74/74A cannot proceed without prior scrutiny under Section 61, the Court clarified that Section 61 applies where demand is based on scrutiny of returns. However, in cases where the foundation of demand is a search under Section 67, the statutory procedure under Section 61 is not mandatory.
The Court also upheld the validity of issuing a consolidated show-cause notice for multiple financial years, relying on precedent set by a Coordinate Bench in M/s Tata Projects Ltd v. Union of India (2026 SCC Online GAU 3798). The Court instructed that liability for each financial year must be separately determined, applying the relevant statutory provisions.
On the penalty imposition under Section 75(13), the Court noted that this provision prevents double penalties for the same act but does not bar the department from proposing penalties under multiple sections initially. The adjudicating authority must ensure compliance with this safeguard.
Crucially, the Court emphasized that allegations of suppression, fraud, and willful misstatement founded on business records, software data, and third-party information require factual adjudication. The petitioner is entitled to contest these allegations, reconcile figures, and present explanations before the authority.
The Court declined to interfere at the writ stage with the show-cause notice and search proceedings, underscoring that the factual disputes necessitate statutory adjudication. However, as a measure of fairness, it granted the petitioner 45 days from the date of judgment to submit its reply to the notice, with the adjudicating authority directed to decide the matter in accordance with law.
This ruling reinforces the principle that procedural lapses or non-disclosure at the initiation stage do not automatically invalidate GST demand notices where statutory conditions are met, and that factual disputes, especially on suppression and tax liability, require a full adjudicatory process.
Bottom Line:
Challenge to demand-cum-show-cause notice under GST Act on grounds of procedural lapses, jurisdictional issues, and alleged suppression of taxable supplies - Court held adjudication by the authority necessary to determine validity of notice and allegations.
Statutory provision(s):
Central Goods and Services Tax Act, 2017 Sections 61, 67, 74, 74A, 75(13), 122; Constitution of India Article 226
M/s HD Associates v. Union of India, (Gauhati) : Law Finder Doc Id # 2974674