Court holds that fees collected for forest permits and entry are sovereign functions of State Government and cannot be taxed as "Tour Operator" services under the Finance Act, 1994
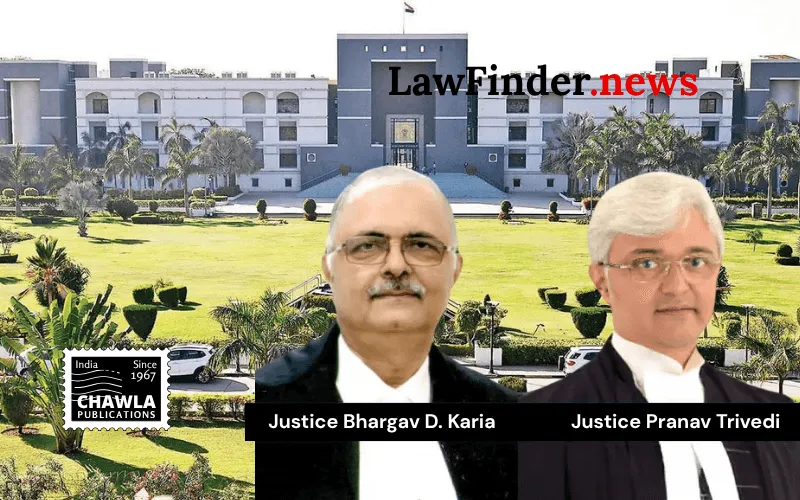
In a significant ruling delivered on August 6, 2026, the Gujarat High Court (Division Bench comprising Justices Bhargav D. Karia and Pranav Trivedi) dismissed the tax appeal filed by the Commissioner of Central Excise and Central Goods and Services Tax, Bhavnagar, against the Office of the Deputy Conservator of Forests, Gir Forest, Junagadh. The appeal challenged the earlier decision of the Customs, Excise & Service Tax Appellate Tribunal (CESTAT), which had held that the activities performed by the Deputy Conservator of Forests-such as issuing permits for entry into forests, collecting entry fees, and camera charges-did not fall within the ambit of taxable "Tour Operator" services under the Finance Act, 1994.
The appellant Revenue had sought to classify the Deputy Conservator of Forests as a "Tour Operator" under sections 65(105)(zzzzw) and 65(105)(n) of the Finance Act, 1994, alleging that the official was engaged in the business of planning, scheduling, or arranging tours and thus liable to pay service tax on fees collected from tourists visiting the Gir Forest and Devaliya Park. The Commissioner had issued show-cause notices and confirmed demands of service tax amounting to over Rs. 3.44 crore, along with interest and penalties.
However, the High Court upheld the CESTAT's findings that these activities were sovereign functions performed by the Deputy Conservator of Forests in his official capacity as an officer of the Government of Gujarat. The fees collected were not commercial charges but statutory levies credited directly to the consolidated fund of the State Government. The Court emphasized that under Article 246(3) of the Constitution of India, matters related to forest conservation fall under the State List, conferring exclusive legislative powers on the State Government to levy such fees. Therefore, the Central Government could not impose service tax on these statutory charges.
The Court observed that the Deputy Conservator of Forests does not act as a private service provider but discharges public duties to protect and conserve forests. It further noted that even if any legal challenge existed, it would lie against the State Government and not the officer personally. The Court found no merit in the Revenue's appeal and held that no substantial question of law arose warranting interference with the Tribunal's order.
This ruling reinforces the principle that sovereign functions and statutory fees collected by State Government officers in the discharge of their official duties are exempt from taxation under the Finance Act, 1994. It provides clarity on the non-applicability of service tax on forest conservation-related fees and safeguards the rights of State authorities carrying out environmental protection activities.
Bottom Line:
Activities undertaken by the Deputy Conservator of Forests in his official capacity for conservation of forests and collection of fees like permit charges, entry fees, and camera charges are sovereign functions of the State Government and cannot be taxed under the Finance Act, 1994 as "Tour Operator" services.
Statutory provision(s): Finance Act, 1994 Sections 65(105)(zzzzw), 65(105)(n), Section 69, Section 73(2), Section 75, Section 77(1)(a); Constitution of India Article 246(3)