Court rejects challenge to CBIC circulars, says GST adjudication order under Section 74 should be tested before appellate authority; directs appeal not to be dismissed on limitation grounds
Patna, Sept. 18, 2026: The Patna High Court has upheld the validity of key CBIC circulars assigning functions of “proper officer” to Central Tax Officers under the GST regime and declined to interfere with a demand order passed against M/s Moral Pharmaceuticals Private Limited, holding that the company has an effective statutory remedy by way of appeal.
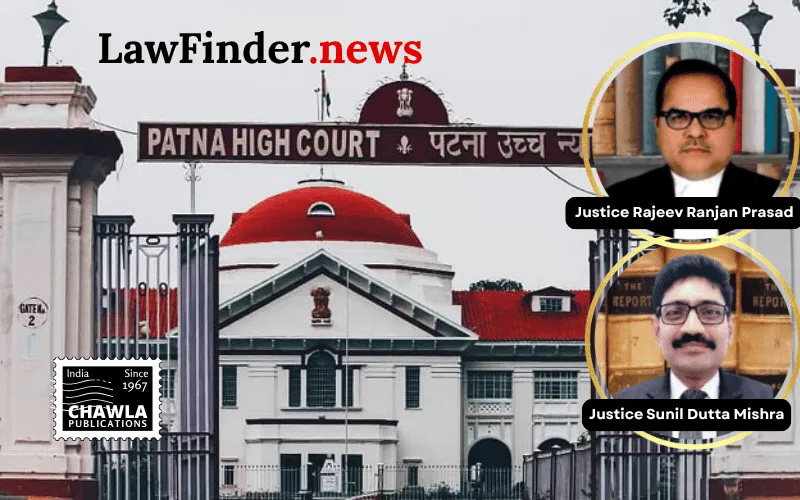
A Division Bench of Justice Rajeev Ranjan Prasad and Justice Sunil Dutta Mishra dismissed the writ petition filed by the Patna-based pharmaceutical company, which had challenged Circular No. 3/3/2017-GST dated 05.07.2017, Circular No. 31/05/2018-GST dated 09.02.2018, and Circular No. 169/01/2022-GST dated 12.03.2022. The petitioner had argued that the Board lacked authority to issue these circulars and that the show-cause notice and subsequent demand order were therefore without jurisdiction.
The court rejected that contention, agreeing with the reasoning of the Bombay High Court in Fomento Resorts & Hotels Ltd. and distinguishing the Supreme Court’s decision in Canon India Pvt. Ltd. v. Commissioner of Customs. The Bench noted that the officers issuing the notice were already Central Tax Officers, and the circulars only assigned them functions as proper officers under the CGST/BGST framework. The court held that the statutory scheme under Sections 3, 4 and 5 of the CGST Act supported such assignment.
The case arose from allegations that the petitioner had short-paid GST by declaring incorrect taxable turnover for FY 2017-18. According to the department, tax amounting to over Rs. 5.10 crore was recoverable under Section 74 of the CGST/BGST Act, along with interest and penalty. The adjudicating authority later confirmed a demand of Rs. 2.91 crore each under CGST and BGST, besides interest and penalty, after holding that the company had suppressed turnover and misstated its returns.
Before the High Court, the petitioner also challenged the proceedings on grounds including absence of digital signature, alleged non-compliance with mandatory preconditions, limitation, and violation of natural justice. However, the court found that the adjudicating authority had considered the reply and documents filed by the company and had also granted a personal hearing. The Bench observed that the issues raised would require factual reappreciation, which is the domain of the appellate authority and not the writ court.
Relying on settled law on alternative remedies, including CIT v. Chhabil Dass Agarwal, the court held that none of the exceptional circumstances justifying writ interference were present in the case. It therefore refused to entertain the challenge to the adjudication order under Article 226 of the Constitution.
However, the court granted liberty to the petitioner to file a statutory appeal within 30 days. It also directed that the appellate authority should not reject the appeal on limitation grounds, noting that the writ petition had been pending before the High Court and was filed within 30 days after the expiry of the normal appeal period under Section 107(4) of the CGST/BGST Act.
The judgment reinforces the legal position that GST adjudication disputes should ordinarily be pursued through the statutory appellate mechanism, while also affirming the validity of CBIC’s circular-based assignment of functions to Central Tax Officers.
Bottom Line :
GST - Challenge to CBIC circulars assigning functions of “proper officer” to Central Tax Officers - Circulars upheld - Canon India distinguished - Writ against adjudication order under Section 74 CGST/BGST not entertained in view of efficacious alternative statutory appeal - Petitioner granted liberty to file appeal and appellate authority directed not to reject on limitation ground.
Statutory provision(s): Sections 2(91), 3, 4, 5, 9, 50, 59, 61, 73, 74, 75, 107, 122(2)(b) of the CGST Act, 2017, corresponding provisions of the BGST Act, 2017, Rule 26(3), Rule 59, Rule 88B of the CGST/BGST Rules, 2017, Article 226 of the Constitution of India