Court Rules Customized Software Development and Digital Signature Certificate Issuance Constitute Pure Services, Not Sale of Goods, Hence Not Subject to VAT under Telangana Value Added Tax Act, 2005
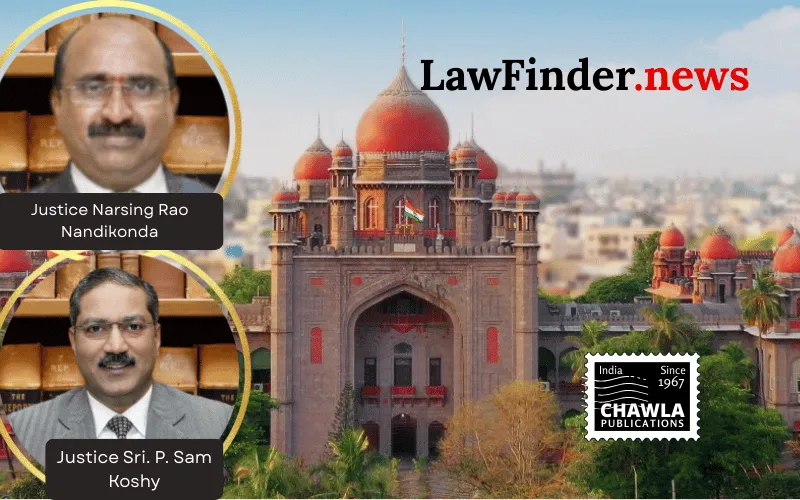
In a landmark judgment delivered on August 24, 2026, a Division Bench of the Telangana High Court, comprising Justices P. Sam Koshy and Narsing Rao Nandikonda, set aside a massive Value Added Tax (VAT) demand of Rs.52,39,44,119 imposed on Tata Consultancy Services (TCS) by the Assistant Commissioner (Commercial Tax), Hyderabad Rural Division. The VAT was levied on TCS's service turnover amounting to over Rs.1,150 crore for the assessment years 2010-11 to 2012-13, primarily concerning custom-made software development, business process outsourcing, and issuance of digital signature certificates.
The Court found the VAT demand to be wholly unsustainable in law and on facts, affirming that the transactions in question were service contracts rather than sale of goods. The judgment clarified that the development of custom-made or customized software, as well as the issuance of digital signature certificates by TCS, do not involve the transfer of property in goods, a necessary ingredient for VAT applicability under the Telangana Value Added Tax Act, 2005 (TGVAT Act). Instead, these transactions are purely services, for which TCS had already discharged service tax liabilities under the Finance Act, 1994.
The case arose when the commercial tax authorities levied VAT on the turnover received by TCS towards various services, treating custom software development and digital signature certificate issuance as sales of goods. The petitioner challenged the Assessment Orders dated March 18 and March 22, 2016, claiming that the transactions were service contracts and thus exempt from VAT.
The Court examined the contractual terms between TCS and its clients, including agreements with Tata Teleservices Limited and Tata Projects Limited. It observed that the intellectual property rights in the custom software developed either vest with the client from inception or are momentarily held by TCS only to grant a perpetual license to the client. The software developed is tailor-made for specific clients on a "work for hire" basis and cannot be marketed or sold to third parties, unlike "unbranded software" which is sold off the shelf and considered goods.
Regarding digital signature certificates, the Court held that issuance of such certificates by TCS, a licensed Certifying Authority under the Information Technology Act, 2000, is purely a service. The transaction does not involve any transfer of goods and is therefore not taxable under VAT laws.
The judgment also relied on precedents from the Supreme Court and Andhra Pradesh High Court, which distinguished between branded/unbranded software and customized software in the context of taxability. The Court underscored that the absence of the essential element of "transfer" of property in goods precludes the applicability of VAT, and such contracts fall under taxable service categories, for which service tax was duly paid.
Consequently, the Telangana High Court quashed the VAT demand and set aside the assessment orders. This decision provides clarity on the tax treatment of custom software services and digital certificate issuance, protecting IT companies from erroneous VAT demands and reinforcing the distinction between sale of goods and provision of services in the digital economy.
Bottom Line:
Levy of VAT on service turnover of a company providing custom-made software, digital signature certificates, and related services under the Telangana Value Added Tax Act, 2005, held to be unsustainable as the transactions were service contracts and not sales of goods.
Statutory provision(s):
Telangana Value Added Tax Act, 2005 - Sections 2(28), 4, 5; Finance Act, 1994 - Section 65(104c); Information Technology Act, 2000