Bench upholds CESTAT's order directing provisional release of gold seized under Customs Act, emphasizing supremacy of Section 110A over CBIC Circular No. 35/2017-Cus.
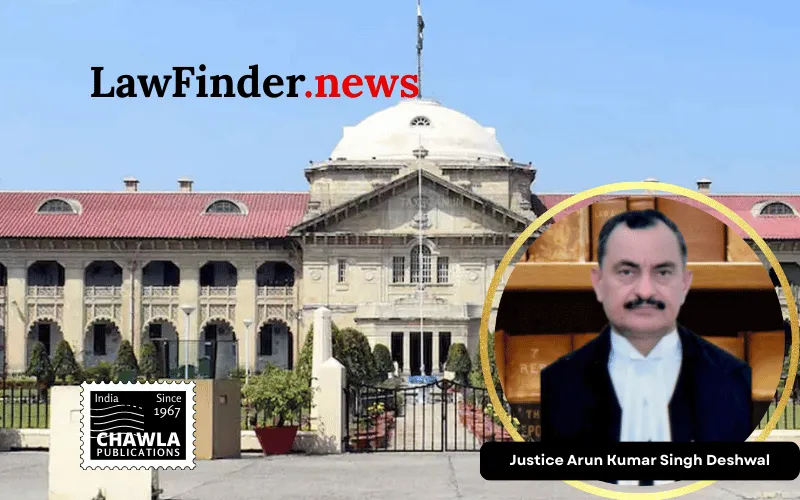
In a significant judgment dated August 31, 2026, the Allahabad High Court (Division Bench, Lucknow) decisively held that the Central Board of Indirect Taxes and Customs (CBIC) Circular No. 35/2017-Cus, which restricts the provisional release of certain seized goods, cannot override the statutory provisions of Section 110A of the Customs Act, 1962. The Court dismissed an appeal filed by the Commissioner of Customs (Preventive), Lucknow, against an order of the Customs, Excise and Service Tax Appellate Tribunal (CESTAT) directing the provisional release of gold and gold jewellery seized from the respondent, Shri Suresh Chand Gupta.
The case arose after officers of the Directorate of Revenue Intelligence intercepted a vehicle in Lucknow in August 2024, recovering seized gold articles. The respondent applied for provisional release of the seized goods under Section 110A of the Customs Act, but the application was rejected by the Additional Commissioner of Customs and subsequently by the Commissioner (Appeals). The respondent then appealed to the CESTAT, which granted provisional release subject to conditions.
The Revenue challenged the CESTAT order before the High Court, raising three main questions: whether CESTAT had jurisdiction to order provisional release after adjudication; whether the statutory presumption regarding smuggled gold and the reverse burden of proof justified denial of release; and whether the respondent's withholding of material facts invalidated the release order.
The Court noted that the adjudicating order confiscating the gold had been set aside by the Commissioner (Appeals) before the CESTAT's order, thus negating the Revenue's first and third contentions. The key issue was the applicability of the CBIC Circular No. 35/2017-Cus, which prohibits provisional release of goods notified under Section 123 of the Customs Act, including gold.
Relying on a precedent set by the Delhi High Court in Additional Director General (Adjudication) v. Its My Name Pvt. Ltd. (2021), the Allahabad High Court affirmed that executive circulars or instructions cannot dilute or supplant express statutory provisions. Section 110A of the Customs Act provides for provisional release of seized goods, and no subordinate legislation, including CBIC Circulars, can override this right. The Court underscored that while executive instructions may supplement the statute, they cannot contradict or nullify it.
Consequently, the Court upheld the CESTAT's direction for provisional release of the seized gold, emphasizing that statutory rights under Section 110A prevail over contradictory circular instructions. The appeal was dismissed, reinforcing the principle that subordinate legislation cannot contravene the parent statute.
This ruling is a landmark affirmation of the supremacy of statutory law over executive circulars in customs proceedings and clarifies the legal position regarding provisional release of seized goods, particularly valuable items like gold, amidst smuggling allegations.
Bottom Line:
Customs Act, 1962.
Statutory provision(s):
Customs Act, 1962 Section 110A, Section 123; CBIC Circular No. 35/2017-Cus.