Court highlights procedural inadequacies and adjudicating authority's inability to analyze voluminous e-way bills and invoices in Rs. 19.36 billion tax demand case under CGST Act
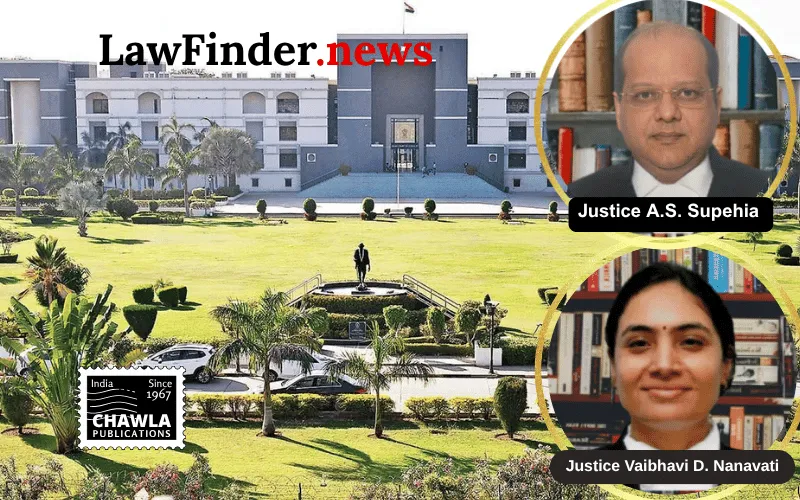
In a significant development, the Gujarat High Court bench comprising Justices A.S. Supehia and Vaibhavi D. Nanavati has granted ad-interim relief to M/s Ford India Private Limited against show-cause notices and Orders-in-original issued under Section 74 of the Central Goods and Services Tax (CGST) Act, 2017. The orders pertain to allegations of wrongful availment of Input Tax Credit (ITC) involving a massive tax demand running into several crores for the financial year 2018-19.
The petitioner, Ford India, challenged the impugned orders issued by the adjudicating authority that relied on audit queries from the Director General of Audit (Central), Ahmedabad. The audit alleged suppression in taxable value compared to e-way bills, triggering the issuance of notices invoking the extended five-year period under Section 74 of the CGST Act. The petitioner contended that the adjudicating authority failed to appropriately analyze the extensive data submitted, including around 4.5 lakh e-way bills and 2.5 lakh invoices, citing the absence of any procedural mechanism to reconcile these records effectively. Despite the voluminous documentary evidence supplied, the authority summarily dismissed the submissions without calling for additional material or clarifications.
Senior Advocate Mihir Joshi, representing Ford India, submitted that the adjudicating officer did not follow the mandated procedure under Section 61 of the CGST Act, which requires scrutiny and verification of inconsistencies through proper inquiry before initiating demand. He stressed that no suppression or evasion was evident and that the petitioner was not afforded a fair opportunity to explain the discrepancies noted by the audit.
On the other hand, the respondents argued that the petitioner failed to furnish complete details and that the burden under Section 155 of the CGST Act to prove the correctness of ITC claim lay with the taxpayer. They maintained that the authority's actions, including issuing the show-cause notices and orders, were justified and lawful.
The Court, after hearing both sides, observed that the adjudicating authority openly admitted its inability to analyze the delivery channels, e-way bills, and invoices due to lack of an effective mechanism. The order records that the authority found it impossible "to ascertain which particular invoices were affected" among thousands of entries submitted in Excel format. The Court noted that the petitioner was never asked to provide additional evidence, which raises concerns about procedural adequacy and fairness.
Given the complexity of the case and the enormous amounts involved, the Court declined to quash the proceedings but allowed the interim relief granted earlier to remain in force until the final adjudication of the petitions. The judgment underscores the need for procedural rigor and adequate mechanisms to handle voluminous GST data before holding taxpayers liable for alleged wrongful ITC claims.
This ruling sets an important precedent emphasizing that tax authorities must conduct detailed and fair examination of evidence, especially in cases involving complex reconciliations of e-way bills and invoices, to prevent arbitrary demands on taxpayers.
Bottom Line:
CGST Act - Show-cause notices and Orders-in-original under Section 74 of the CGST Act, 2017 challenged - Held, inability of adjudicating authority to analyze delivery channels, e-way bills, and invoices due to lack of mechanisms raises concerns about procedural adequacy - Ad-interim relief granted to petitioner till final disposal.
Statutory provision(s):
Central Goods and Services Tax Act, 2017 - Sections 61, 74, 155; Goods and Services Tax Rules, 2017 - Rule 99
M/s Ford India Private Limited v. Union of India, (Gujarat)(DB) : Law Finder Doc Id # 2979304