Court directs refund of Rs. 6.41 lakh with interest to Madras Club after finding partial tax burden passed on to members; underscores that refund claims under Central Excise Act, 1944, must consider unjust enrichment principle.
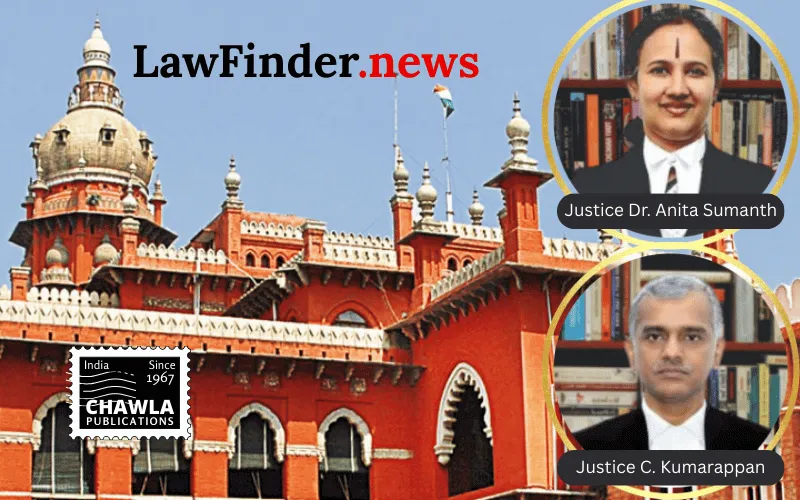
In a significant ruling delivered on September 1, 2026, the Madras High Court (Division Bench comprising Justices Dr. Anita Sumanth and C. Kumarappan) partially allowed the appeal of M/s The Madras Club against the Commissioner of GST & Central Excise, Chennai South Commissionerate, Chennai, concerning a refund claim of service tax paid under protest.
The dispute arose when the Madras Club, registered under the Service Tax Department for providing "Membership of Club or Association Service," faced a demand of Rs. 29,24,687 towards subscription amounts received from its members. The Club challenged this demand before the Commissioner (Appeals), which was set aside, and the decision upheld by the Customs, Excise and Service Tax Appellate Tribunal (CESTAT). Subsequently, the Club sought a refund of Rs. 15,51,086 paid pursuant to the demand.
The key legal question centered on whether the refund claim could be granted despite the Club having collected part of the tax amount from its members, thereby potentially passing on the tax burden. The Madras High Court reiterated the well-established principle under Section 11B of the Central Excise Act, 1944 - refund claims are subject to the doctrine of unjust enrichment. This doctrine prevents a taxpayer from receiving a refund if the tax burden was passed on to others.
Relying heavily on the Supreme Court precedent in Mafatlal Industries Ltd. v. Union of India (1997) 5 SCC 536, the Court held that the refund is only permissible to the extent the taxpayer has not passed the burden of tax to another party. The Court carefully examined the Auditor's Certificate submitted by the Club, which disclosed that Rs. 9,09,717 had already been recovered from members, while Rs. 6,41,369 remained uncollected. Therefore, the Court concluded that the Club was entitled to refund only the amount not passed on - Rs. 6,41,369 - along with applicable interest as per Section 11BB of the Central Excise Act.
The Court also addressed the contention regarding the relevance of the Auditor's Certificate. While acknowledging that such certificates are pertinent, the Court emphasized the necessity of verifying their authenticity and accuracy. The Court found that the Club's own records evidenced partial recovery of tax from members, thereby restricting the refund claim.
In its final order, the Madras High Court set aside the CESTAT's dismissal of the refund claim and directed the authorities to process the refund of Rs. 6,41,369 with applicable interest within eight weeks. The Court declined to impose any costs on the parties.
This judgment underscores the judiciary's consistent approach in balancing taxpayers' rights to refunds with the State's interest in preventing unjust enrichment. It also clarifies the application of the unjust enrichment doctrine in the context of service tax refunds for membership fees in clubs or associations.
Bottom Line:
Refund of service tax under Section 11B of the Central Excise Act, 1944 is subject to the doctrine of unjust enrichment. Taxpayer must establish that the burden of duty has not been passed on to others to claim refund.
Statutory provision(s):
Central Excise Act, 1944 Section 11B, Section 11BB; Article 265 of the Constitution of India
Madras Club v. Commissioner of GST & Central Excise, (Madras)(DB) : Law Finder Doc Id # 2979421