Court Declines to Quash Section 148 Notices, Emphasizes Adjudication of Disputed Facts Through Proper Income Tax Authorities; Allegations of Mala Fides and Bias Dismissed Due to Delay
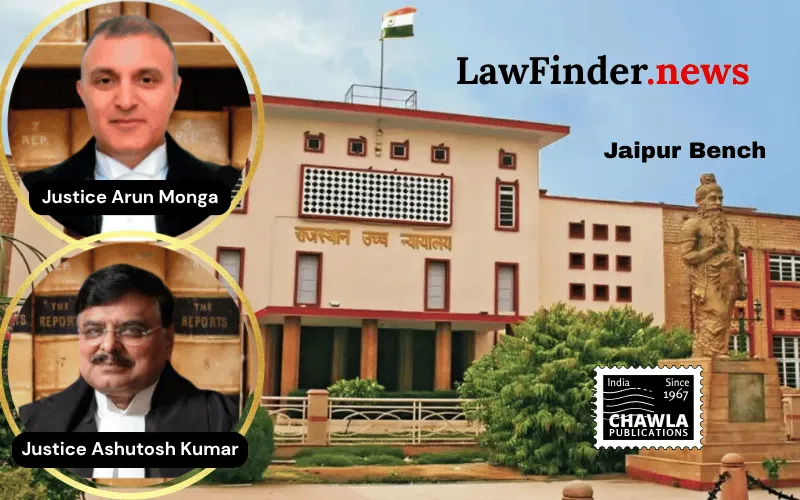
In a significant judgment dated August 21, 2026, the Division Bench of the Rajasthan High Court, Jaipur Bench, comprising Justices Arun Monga and Ashutosh Kumar, delivered its verdict in the writ petition filed by Mahesh Kumar Gupta challenging reassessment notices issued under Section 148 of the Income Tax Act, 1961. The petitioner sought to quash reassessment proceedings initiated for Assessment Years 1995-96 to 1999-2000 on grounds of lack of jurisdiction, non-supply of reasons for belief formation, and mala fide intentions on part of revenue officials.
The Court observed that reassessment proceedings had been initiated following a survey conducted on February 16, 2000, at the petitioner's brick kiln business premises, which revealed discrepancies including excess stock, cash book irregularities, and admitted undisclosed income. Despite the petitioner's contention that all material facts had been disclosed and that reassessment amounted to a mere change of opinion, the Court found that the Assessing Officer had tangible material to form a belief that income had escaped assessment, justifying issuance of notices under Sections 147 and 148.
The petitioner had also raised serious allegations of mala fides against the then Assessing Officer, including unpaid bills and improper demands. However, the Court noted that these allegations involved disputed questions of fact and could not be adjudicated on a writ petition, especially after a lapse of over two decades since the initiation of proceedings. The Court emphasized that the Income Tax Act provides a self-contained adjudicatory process, and such factual disputes must be resolved through appropriate statutory mechanisms.
Rejecting the petitioner's plea to quash the reassessment notices, the Court directed him to respond to the notices before the competent Income Tax authorities and avail statutory appellate remedies if aggrieved by any adverse orders. The Court also clarified that all issues raised by the petitioner remain open for consideration by the Assessing Officer under the Income Tax Act.
This judgment reaffirms the principle that writ courts should not bypass the statutory adjudicatory process in matters involving disputed factual questions related to income tax assessments. It also underscores the importance of timely resolution through appropriate forums rather than protracted litigation spanning decades.
Bottom Line:
Income Tax - Reassessment proceedings initiated under Sections 147 and 148 of the Income Tax Act, 1961 - Writ petition challenging notices under Section 148 on the grounds of lack of jurisdiction, non-supply of reasons, and allegations of mala fides - Court held that disputed questions of fact cannot be adjudicated in a writ petition and directed the petitioner to respond to notices under the Income Tax Act before the competent authority.
Statutory provision(s):
Income Tax Act, 1961 - Sections 133A, 143(1)(a), 143(3), 147, 148, 271B, 277
Mahesh Kumar Gupta v. Union of India, (Rajasthan)(DB)(Jaipur Bench) : Law Finder Doc Id # 2979285